Best Business Travel Credit Cards for Canadians in 2026
Best business travel credit cards for Canadians in 2026 compared by FX fees, rewards, and expense tools. Find the card to cut costs and simplify travel spend.


Trusted by 15,000+ Canadian businesses
Business banking for Canada
Local CAD and USD accounts, corporate cards with cashback, the lowest FX rates in Canada, free local transfers, and more.
Business travel expenses represent one of the largest controllable costs for Canadian companies. The best business travel credit cards for Canadians can save your company thousands each year. The wrong card buries those savings in hidden fees.
Foreign transaction fees typically add 2.5% to 3% to every international purchase. For businesses buying from U.S. vendors, paying international contractors, or sending employees abroad, these fees compound quickly. A company spending $50,000 annually in foreign currencies can lose $1,250 to $1,500 in FX fees alone.
Not all "no FX fee" cards deliver equal value. Some waive the explicit fee but convert at poor exchange rates, hiding costs in the spread. Others offer genuine savings but lack the expense management features modern businesses need.
This guide compares the best business travel credit cards for Canadians in 2026. You will find category winners, comparison tables, true-cost calculations, and a framework to match your business with the right card.
What Canadian Businesses Need In A Business Travel Credit Card For 2026
Business credit cards typically offer higher credit limits than personal cards. That makes it easier to manage cash flow, handle major purchases, and cover unexpected costs. The rewards can also be tailored to your operations, so frequent-flyer teams can earn travel rewards for specific hotel chains or airlines.
Employee card management stands out as a significant advantage. Most issuers let you add multiple employee cards to the primary account, streamlining expense tracking and consolidating rewards. This proves particularly valuable for businesses with several team members making regular purchases.
Understanding the difference between credit cards and charge cards matters for business use. Traditional credit cards offer revolving credit but carry interest charges averaging 19.99% and complex fee structures. Charge cards require full monthly payment but usually offer simpler pricing, better expense management, and stronger banking integration.
For businesses with healthy cash flow, charge cards often deliver better net value. They eliminate interest while adding superior operational features.
Evaluation Criteria for Business Travel Cards:
- Foreign transaction fees and FX rates
- Rewards structure and redemption flexibility
- Annual fees versus value delivered
- Travel insurance coverage
- Expense management and accounting integration
- Employee card capabilities
- Lounge access and travel perks
Compare The Best Business Travel Credit Cards For Canadians At A Glance
Note: FX rates and fees are subject to change. Verify current rates before applying.
Best Business Travel Credit Cards In Canada For 2026, By Category
Best Overall For Multi-Currency Business Operations: Venn Mastercard Charge Card
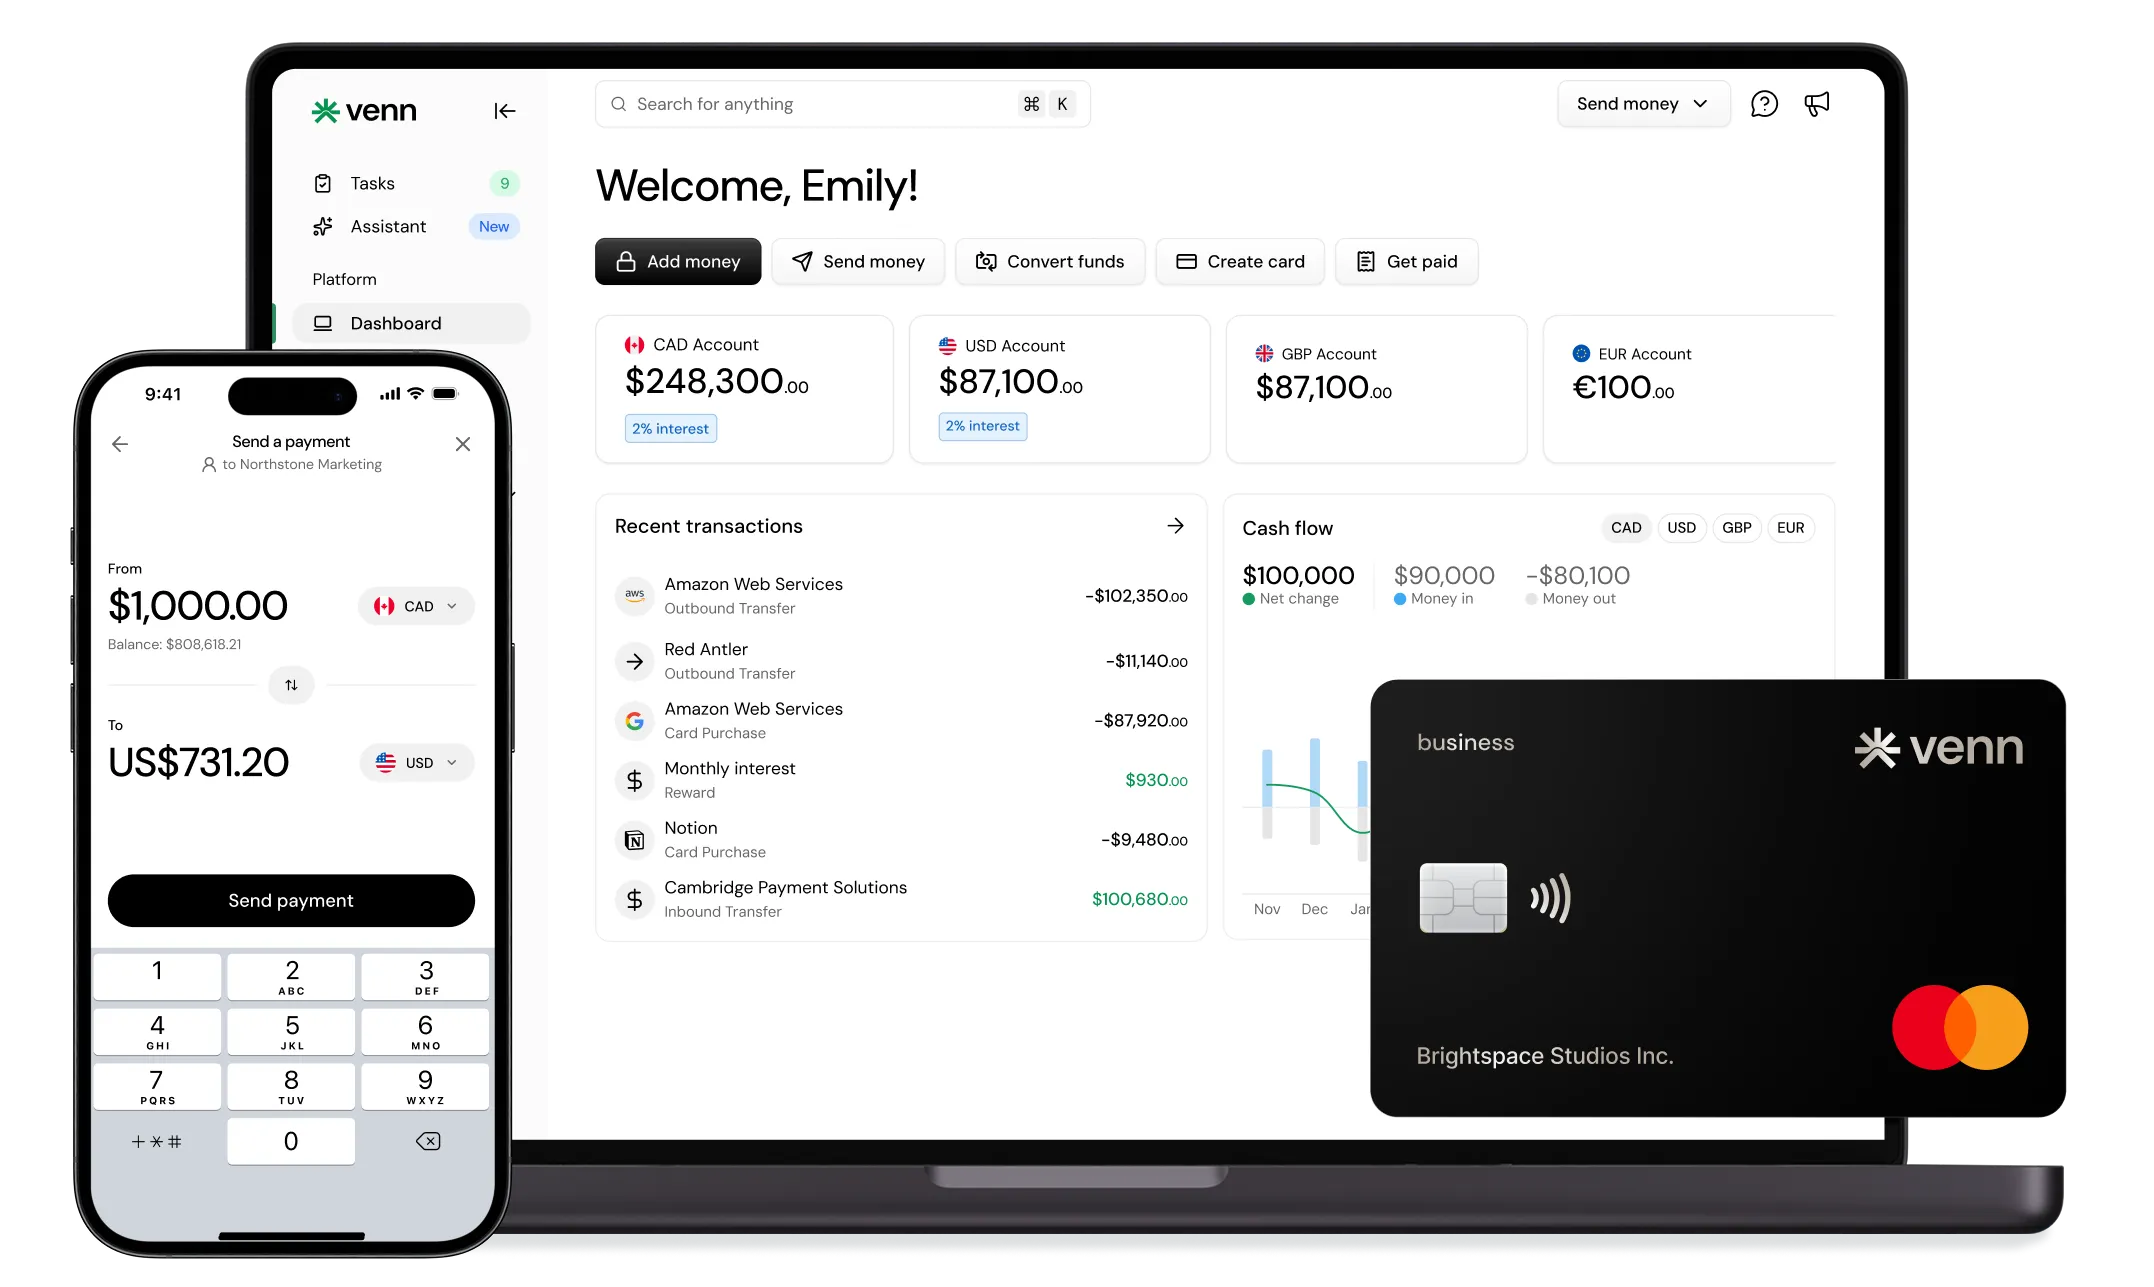
Venn's corporate card goes beyond simply waiving foreign transaction fees. It automatically charges purchases in the currency you're spending in (USD, CAD, EUR, or GBP), drawing from your corresponding multi-currency account. This eliminates unnecessary conversions and saves more than cards that waive fees but still convert at marked-up rates.
You get real local accounts in CAD, USD, EUR, and GBP, with FX conversion from 0.25% to 0.45% depending on your plan. You also earn 1% cashback on card spend, up to $5,000 per month on the Essentials plan and unlimited on the Pro plan.
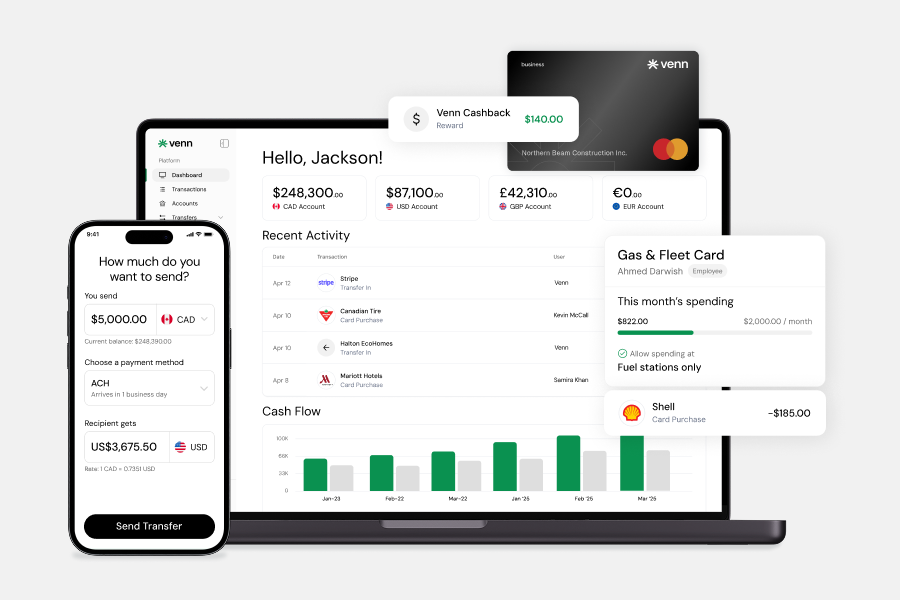
The platform includes built-in expense management, OCR receipt capture, and two-way sync with QuickBooks and Xero, eliminating separate tools. From the mobile app, teams can view balances, send transfers, and issue cards without switching platforms.
The card automatically uses the currency you're paying in first. For businesses receiving USD payments through Stripe, Shopify, or PayPal, funds land directly in a real US account with ACH capabilities. You avoid cross-border card conversion fees, then spend those USD without converting again.
Pros:
- FX from 0.25% to 0.45% depending on plan
- Multi-currency card that auto-selects the spending currency
- 1% cashback on card spend, up to $5,000/month on Essentials and unlimited on Pro
- Built-in expense management and accounting sync
- No monthly fees on the Essentials plan
- 2% interest on all CAD and USD balances, with a limited-time boost of 2.75% on CAD and up to 3.5% on USD balances over $1 million (learn more)
- Real local accounts (CAD, USD, EUR, GBP)
- Funds covered under CDIC insurance protection
Cons:
- Charge card (requires full monthly payment)
- No airport lounge access
- Not available in Quebec
Best For: SMBs and startups with international operations, multi-currency needs, or a goal of consolidating financial tools into one platform.
Verdict: For Canadian businesses that spend across currencies, Venn pairs low FX rates with an all-in-one platform that single-purpose travel cards cannot match.
Best For No Foreign Transaction Fees: Scotiabank Passport Visa Infinite Business
Scotiabank's Passport Visa Infinite Business is one of the few traditional bank cards in Canada that waives foreign transaction fees entirely. It suits businesses that travel frequently and want to earn Scene+ points on international purchases without paying FX fees. The card also offers solid travel perks, including airport lounge access and travel insurance.
The card earns a steady 1.5% back in Scene+ points, along with a welcome bonus of up to 40,000 Scene+ points. Many business cards charge a 2.5% foreign transaction fee and offer lower rewards. The $199 annual fee can pay off for businesses with significant foreign-currency spend.
You get a comprehensive insurance package, lounge access, car rental discounts, and Visa Infinite benefits. The limitation is that it lacks multi-currency functionality and requires separate products for USD accounts or expense tracking.
Pros:
- No foreign transaction fees
- 6 free airport lounge passes annually
- Comprehensive travel insurance
- Scene+ points flexibility
Cons:
- Annual fee of $199
- No multi-currency accounts
- No built-in expense management
Best For: Established businesses with existing Scotiabank relationships that prioritize travel rewards and lounge access.
Verdict: The strongest traditional-bank pick for eliminating FX fees on travel, best when you already bank with Scotiabank.
Best Premium Business Travel Card: American Express Business Platinum
The American Express Business Platinum Card sits at the top of Canada's premium business travel cards. Its $799 annual fee buys a broad benefits package built for companies with substantial travel budgets.
The card earns 1.25 points per dollar on all purchases, which keeps reward tracking simple. An annual $200 travel credit helps offset the fee, and cardholders get extensive airport lounge access worldwide. Travel protection covers emergency medical, trip cancellation, and lost baggage, and a concierge service handles booking requests.
Acceptance is the main limitation, since Amex is not accepted everywhere, especially at smaller international vendors. The 2.5% foreign transaction fee also erodes value on international spend, and the rewards favour travel over everyday costs.
Amex's standard Business Platinum in Canadian dollars remains available and is not being discontinued.
Pros:
- Extensive airport lounge access worldwide
- Hotel elite status (Marriott, Hilton)
- $200 annual travel credit
- Comprehensive travel insurance
- Concierge service
Cons:
- Annual fee of $799
- Foreign transaction fee of 2.5%
- Limited Amex acceptance internationally
- High spend needed to justify the cost
Best For: Established businesses with substantial travel budgets that can maximize premium perks and offset the annual fee.
Verdict: Worth it only for high-volume travellers who will use the lounge access, travel credit, and concierge enough to offset the $799 fee.
Best For Airline Loyalty (Aeroplan): TD Aeroplan Visa Business Card
The TD Aeroplan Visa Business Card offers compelling value for companies that fly Air Canada often. It earns 2x Aeroplan points on Air Canada purchases and 1.5x on eligible business categories. Cardholders also get a free first checked bag on Air Canada flights.
Air Canada has changed how Aeroplan points are earned. Starting January 1, 2026, members earn points on eligible Air Canada flights based on dollars spent rather than distance travelled. This change rewards businesses that book premium fares.
A comprehensive insurance package covers common travel risks. The $149 annual fee often comes with a first-year rebate, and the card works best for businesses already committed to the Air Canada ecosystem.
Pros:
- Strong Aeroplan earning rates on Air Canada
- Free first checked bag on Air Canada
- Elite Status qualifying credits
- First-year fee rebate often available
Cons:
- Foreign transaction fee of 2.5%
- Best value tied to Air Canada loyalty
- Limited expense management features
Best For: Businesses with frequent Air Canada travel that want to maximize Aeroplan points.
Verdict: The go-to card for Air Canada loyalists who want Air Canada travel benefits and will use them enough to justify the fee.
Best For Hotel Rewards: Marriott Bonvoy Business American Express
The Marriott Bonvoy Business American Express Card delivers strong rewards for both travel and everyday business spending. It helps businesses earn Marriott Bonvoy points faster while offering tools to manage expenses.
You earn 5 points per dollar at participating Marriott Bonvoy hotels, 3 on eligible gas, dining, and travel, and 2 on everything else. Points redeem for hotel stays with no blackout dates or for flights with many airlines. You also receive an annual Free Night Award after your card anniversary.
The $150 annual fee is reasonable given the earning potential, and travel insurance covers flight delay, baggage, and car rental. The main drawbacks are the 2.5% foreign transaction fee and limited Amex acceptance.
Pros:
- 5x points at Marriott properties
- Annual Free Night Award
- No blackout dates on redemptions
- Comprehensive travel insurance
Cons:
- Foreign transaction fee of 2.5%
- Limited Amex acceptance
- Best value tied to Marriott loyalty
Best For: Businesses with frequent hotel stays at Marriott properties.
Verdict: The best fit for businesses with regular Marriott stays who can turn nightly earn into Free Night Awards.
Best For Air Canada Flyers On A Budget: CIBC Aeroplan Visa Business
The CIBC Aeroplan Visa Business Card is a lower-cost route into Aeroplan for Air Canada flyers. Its $180 annual fee sits below premium alternatives. The card earns 2x Aeroplan points on Air Canada purchases, 1.5x on eligible business categories, and 1x on everything else.
Unlike the TD Aeroplan Visa Business Card, it carries no automatic lounge access. Instead, you can earn up to four Maple Leaf Lounge passes per year. The standard 2.5% foreign transaction fee applies, and the expense tools are basic.
Pros:
- Lower $180 annual fee for Aeroplan earning
- 2x Aeroplan on Air Canada, 1.5x on business categories
- Up to 4 earned Maple Leaf Lounge passes per year
- Full Aeroplan redemption flexibility
Cons:
- 2.5% foreign transaction fee
- No automatic lounge access
- Basic expense management
- Best value tied to Air Canada loyalty
Best For: Air Canada flyers who want Aeroplan earning at a lower annual cost than premium cards.
Verdict: A budget-friendly Aeroplan option; choose it over the TD card if you want a lower annual cost and can forgo automatic lounge access.
The True Cost Of Business Travel Cards: FX Fees Vs. Rewards Value
Just about every credit card charges foreign transaction fees. Whenever you make a purchase in a non-Canadian currency, you pay an extra rate, typically 2.5%, on top of the exchange rate. Individually the fees seem small, but they add up quickly if you use the card as a primary payment method abroad or for international purchases.
Example: $5,000/month in international spend ($60,000/year)
The difference between the worst and best options exceeds $1,200 annually on modest international spend. For businesses with higher volumes, the savings multiply accordingly.
Traditional "no FX fee" cards eliminate the explicit fee but often convert at rates that include a hidden markup. Venn's approach differs: by holding funds in the currency you need and auto-selecting that currency at point of sale, you avoid conversion entirely when possible. When conversion is necessary, the 0.25% to 0.45% rate keeps FX costs low.
How To Choose The Best Business Travel Credit Card For Your Company
If your business:
- Has significant USD/EUR/GBP transactions → consider multi-currency solutions (Venn)
- Prioritizes airport lounge access → Scotiabank Passport Business or Amex Platinum
- Flies primarily Air Canada → TD or CIBC Aeroplan Business cards
- Stays frequently at Marriott → Marriott Bonvoy Business Amex
- Needs integrated expense management → Venn
- Has limited travel but wants rewards → Traditional bank cards with cashback
Questions to Ask:
- What percentage of your spend is in foreign currencies?
- Do you need employee cards with spending controls?
- How important is accounting software integration?
- Do you value lounge access and travel perks?
- Is your business cash-flow positive, making a charge card viable?
Beyond The Card: Why Modern Businesses Need Integrated Financial Platforms
Traditional business credit cards force you to piece together solutions. You juggle one card for no FX fees, another platform for expense tracking, and a separate USD account. Reconciling everything then falls to manual work, which costs time and creates errors.
Modern platforms consolidate these functions. With Venn, your card spend integrates with your full financial operations. You get 1% cashback on card spend, real-time expense tracking, OCR receipt capture, and two-way sync with QuickBooks and Xero.
Digital receipt capture and OCR technology automatically extract and categorize expense information, cutting the time spent preparing expense reports. For businesses managing international transactions, consolidating these functions into one platform delivers both cost savings and operational efficiency. Sign up for Venn
Frequently Asked Questions
Q: What Is a Foreign Transaction Fee?
A: A foreign transaction fee is a charge added to purchases made in a foreign currency, typically around 2.5%. For businesses with regular international travel or overseas suppliers, those fees can compound quickly across the year.
Q: What's the Difference Between a Credit Card and a Charge Card?
A: A business credit card offers revolving credit with interest, while a charge card generally requires the balance to be paid in full each month. For companies with healthy cash flow, charge cards can provide value by avoiding interest charges and offering stronger expense controls.
Q: How Do Multi-Currency Cards Work for Business Travel?
A: Multi-currency cards let you hold balances in several currencies and spend directly from each one. Cards like Venn's automatically use the currency you're paying in, helping avoid unnecessary conversions and marked-up exchange rates.
Q: Can a Sole Proprietor Qualify for a Business Travel Card?
A: Yes. In our work with Canadian businesses, most business travel cards accept sole proprietors, who typically apply using personal credit and a personal guarantee.
Q: Are Business Travel Cards Worth the Annual Fee?
A: Business travel cards can be worth the annual fee when your foreign exchange savings and rewards exceed that fee. Multiply your annual foreign-currency spend by 2.5% to estimate potential FX savings, then weigh that against the fee and rewards value.
Sources And Methodology: Competitor card figures were verified against published issuer pages and independent sources as of September 2026. Rates and fees change; confirm current terms with each provider before applying.
Disclaimer: This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Venn Software Inc or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional. We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.

Venn is all-in-one business banking built for Canada
From free local CAD/USD accounts and team cards to the cheapest FX and global payments—Venn gives Canadian businesses everything they need to move money smarter. Join 15,000+ businesses today.
Frequently asked questions
Everything you need to know about the product and billing.
Join 15,000+ businesses banking with Venn today
Streamline your business banking and save on your spend and transfers today
No personal credit check or guarantee.