Best Business Bank Accounts for USD and CAD in Canada
Discover the best business bank accounts for USD and CAD. Compare fees, FX rates, and features to find secure, efficient solutions for Canadian businesses.


Trusted by 15,000+ Canadian businesses
Business banking for Canada
Local CAD and USD accounts, corporate cards with cashback, the lowest FX rates in Canada, free local transfers, and more.
Managing USD and CAD transactions through traditional single-currency accounts costs Canadian businesses thousands annually in foreign exchange markups and wire fees. The average business paying U.S. vendors or receiving payments from American clients loses 3-5% on every transaction through hidden fees and unfavorable exchange rates.
This comprehensive guide compares business bank accounts that support both USD and CAD operations. We evaluate each provider's account structure, focusing on whether USD accounts are truly local (enabling ACH transfers) or Canada-based (requiring expensive SWIFT wires). We also analyze FX conversion rates, monthly fees, and platform integration capabilities.
The key factors determining the best multi-currency account include whether the USD account can send and receive ACH payments, the total cost of foreign exchange conversions, transfer fees for both domestic and international payments, and how well the platform integrates with your existing business tools and workflows.
Why Canadian Businesses Need Dual-Currency Business Accounts
Most Canadian businesses interact with USD regularly through U.S. clients, international vendors, e-commerce platforms like Shopify and Stripe, or cross-border contractors. Yet traditional banking infrastructure forces these businesses to choose between expensive conversions or maintaining separate, disconnected accounts for each currency.
E-commerce businesses can also face additional cross-border card processing fees without local USD accounts. The hidden costs of single-currency accounts compound quickly. Banks charge 2.5-3% FX markups on every conversion, turning a $10,000 USD payment into a $250-300 loss. International wire transfers cost $15-30 per transaction, with additional inbound wire fees of $17+ even for USD-to-USD transfers via SWIFT. These transfers also take 3-5 business days to process, creating cash flow delays.
The solution lies in true multi-currency accounts that hold both CAD and USD with local banking capabilities in each currency. These accounts enable businesses to receive payments, pay vendors, and manage operations in the currency of transaction, converting only when necessary at competitive rates. This approach eliminates wire fees for local transfers and reduces FX costs by up to 90%.
Quick Comparison: Best Business Accounts for USD and CAD
Best Business Bank Accounts for USD and CAD: Detailed Reviews
The following sections provide detailed breakdowns of each provider's USD and CAD capabilities, including account structure, costs, limitations, and ideal use cases for Canadian businesses.
1. Venn Multi-Currency Business Account
Best for: Canadian businesses that need real local USD and CAD accounts with the lowest FX rates and integrated automation.
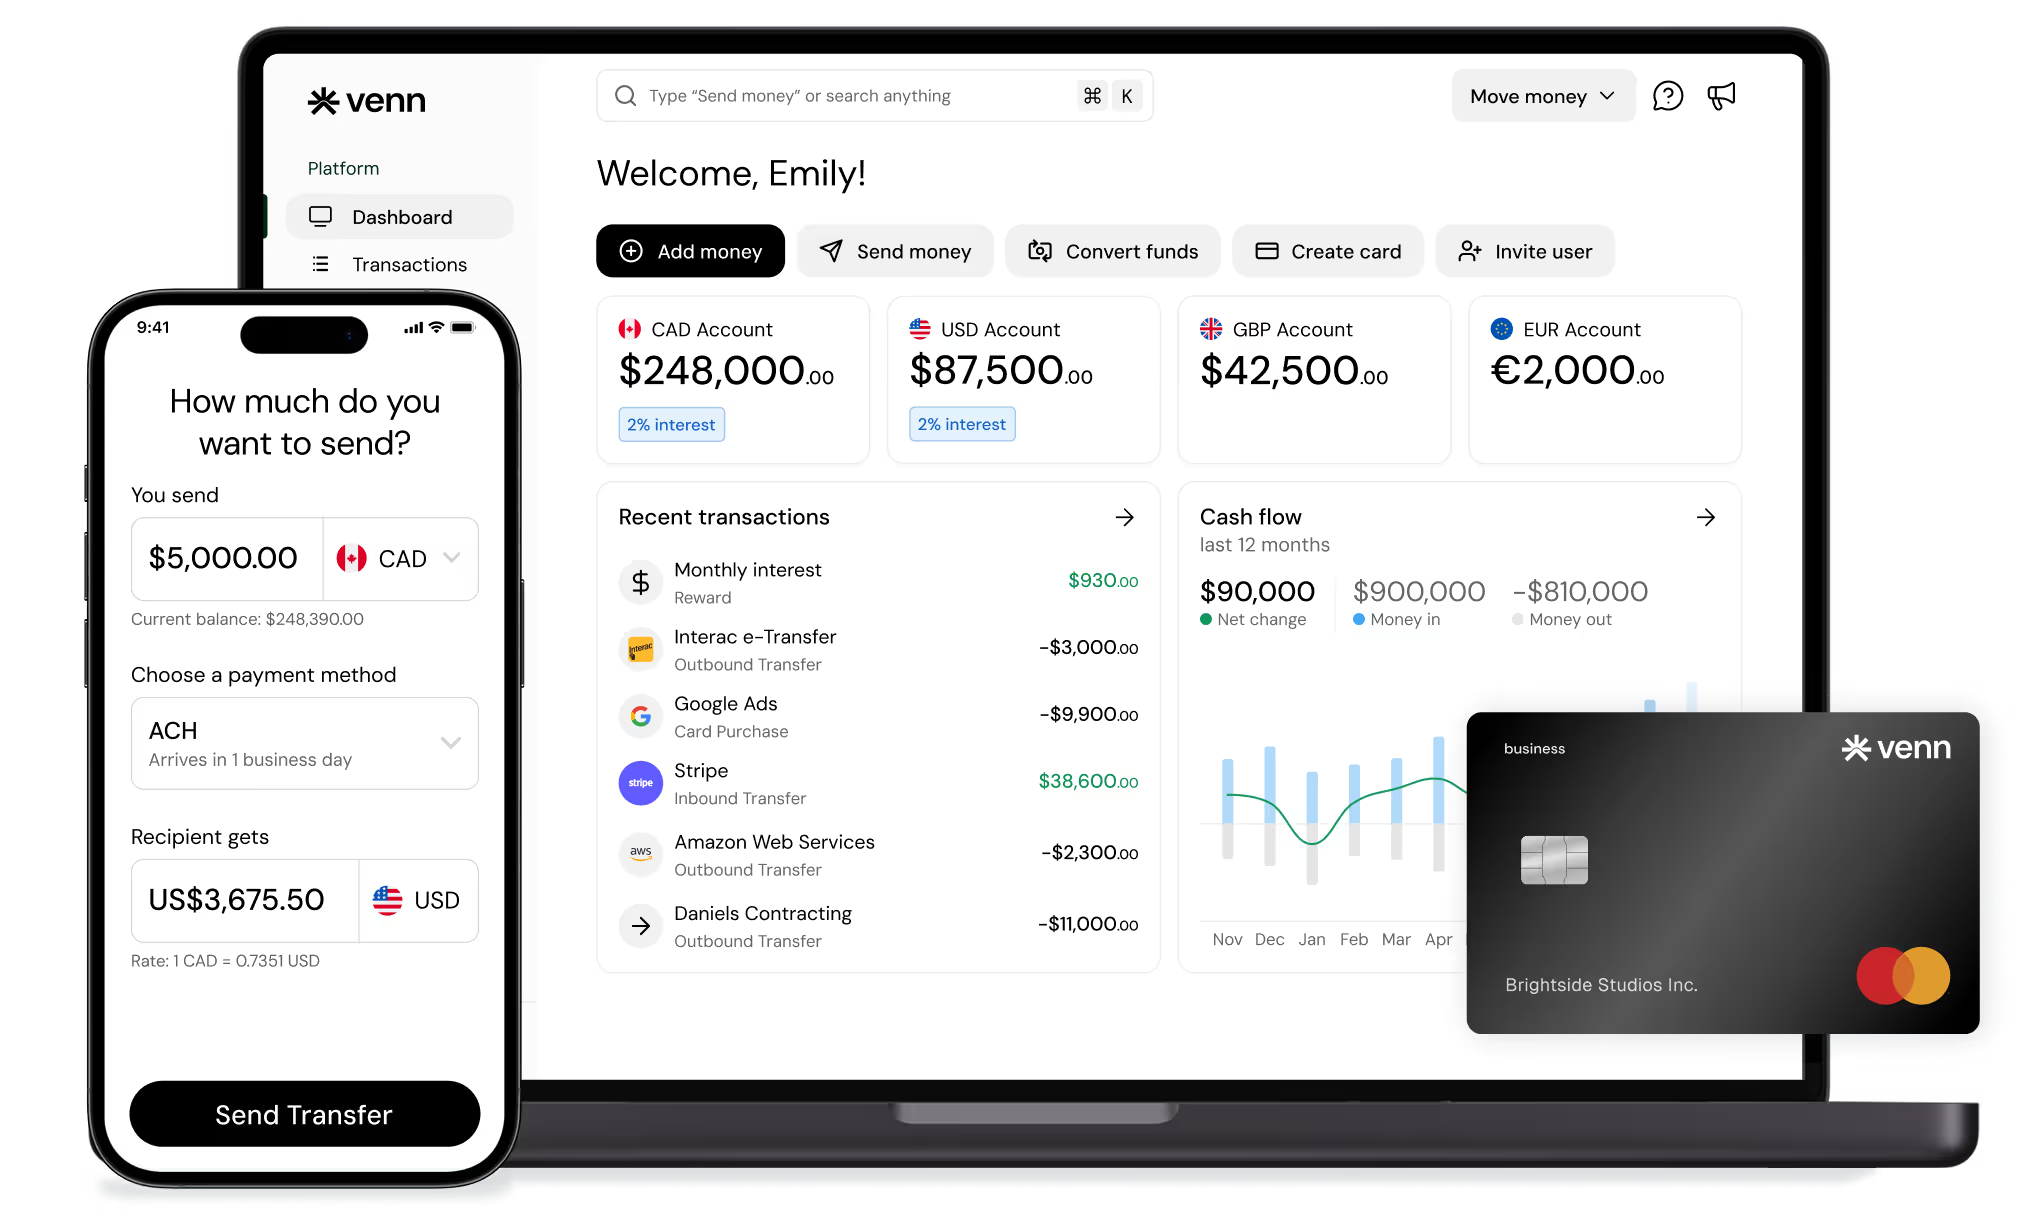
Venn stands alone in offering real local USD accounts with full ACH send and receive capability alongside true Canadian banking infrastructure. This eliminates the wire fees and processing delays that plague traditional bank USD accounts, enabling businesses to operate as locals in both the U.S. and Canada without cross-border friction.
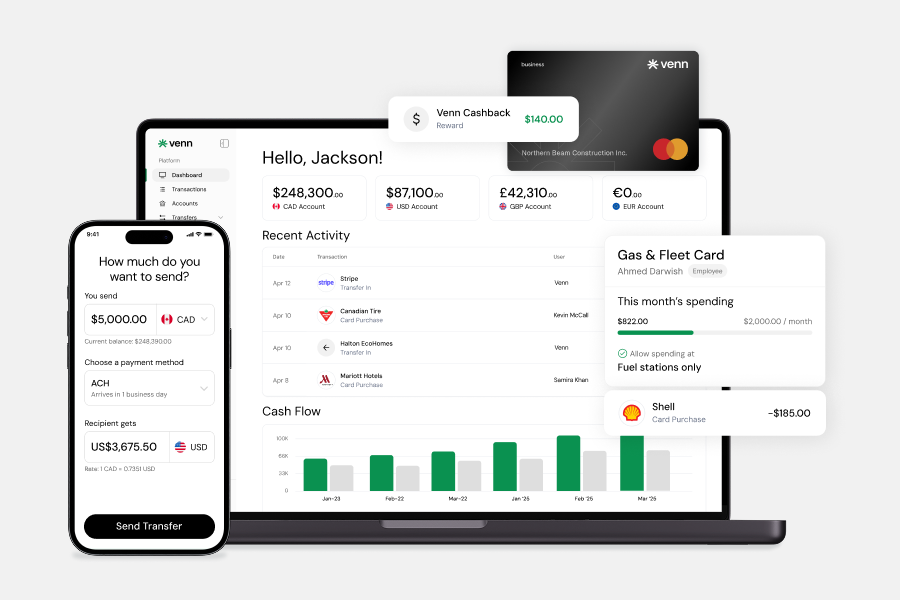
The platform delivers substantial cost advantages through FX rates from 0.25% compared to 2.5-3% at traditional banks, free inbound wires, and outbound wires at just $6-10. The multi-currency corporate card provides 1% cashback on card spend and automatically selects the payment currency to avoid unnecessary conversions. From the mobile app, businesses can access account funds, initiate transfers, and issue new cards directly from their phones. Beyond banking, Venn integrates two-way QuickBooks and Xero sync, automated payables, invoice matching, and expense management into one unified platform.
- Real local USD account with ACH capability
- CAD, USD, GBP, EUR accounts included
- FX rates from 0.25%
- Free unlimited Interac e-Transfers
- 1% cashback on card spend (up to $5,000/month on the free Essentials plan, unlimited on Pro)
- Multi-currency card that auto-selects payment currency
- $0-2 ACH/EFT, $6-10 international wires
- Two-way sync with QuickBooks and Xero
- Built-in invoicing, payables, and expense management
- 2% interest on all CAD and USD balances, with a limited-time boost of up to 2.75% on CAD and up to 3.5% on USD balances (learn more)
- Eligible deposits held at Bank of Montreal, a CDIC member
Learn more about Venn's pricing or explore US banking capabilities.
Verdict: Venn is the only option here that pairs a genuine US-domiciled, ACH-capable USD account with full Canadian banking, the lowest FX tier, and built-in accounting automation.
2. RBC USD Business Account
Best for: Established businesses with existing RBC relationships that need basic USD account access.
RBC offers USD business accounts, but they operate from Canada, meaning all USD transfers rely on SWIFT wires rather than local ACH rails. This structure adds wire fees to every USD transaction and applies FX markups on conversions, making regular cross-border activity expensive.
Key limitations:
- USD account is Canada-based, no ACH capability
- $17+ inbound wire fees for USD transfers
- 2.5-3% FX markup on conversions
- $30+ outbound wire fees
- Separate account setup and login required
- No multi-currency card or cashback
- No accounting software integrations
Verdict: Fine if you already bank with RBC, but the Canada-based USD account and SWIFT-only rails make it costly for regular U.S. payments.
3. TD USD Business Account
Best for: Businesses with high USD volumes that prioritize in-branch service over cost efficiency.
TD's USD business account mirrors the limitations of other major banks. The account is held in Canada, so it cannot send or receive local ACH transfers and relies on SWIFT wires for USD movement. High FX markups and wire fees on both inbound and outbound transfers add up quickly for businesses that transact regularly.
Key limitations:
- Canada-based USD account, no local ACH
- High FX markups (2.5-3.5%)
- Wire fees on inbound and outbound transfers
- No multi-currency card support
- Requires separate account management
- No integration with cloud accounting tools
Verdict: Branch access is the main draw; the 2.5-3.5% FX markup and wire-only USD transfers make it expensive at volume.
4. BMO USD Premium Rate Savings Account
Best for: Businesses that want to hold USD but rarely transact in it.
BMO positions its USD account as a savings vehicle rather than an operating account. It works for parking U.S. dollars, but it is not designed for frequent transactions. Businesses that move USD often will encounter wire fees and FX markups that erode any interest earned.
Key limitations:
- Savings-focused, not transactional
- No ACH capability
- Wire fees apply to transfers
- 2.9% FX markup on conversions
- No multi-currency card
- Separate product from CAD account
Verdict: A reasonable place to park idle USD, but not built for businesses that actually move U.S. dollars.
5. Wise Business Account
Best for: Businesses focused primarily on international payments in multiple currencies beyond USD/CAD.
Wise excels at holding and converting 40+ currencies with transparent FX rates of 0.4-0.6%. The platform provides local account details for USD, GBP, EUR, and other major currencies. However, Wise lacks critical Canadian banking functionality. The platform does not support Interac e-Transfer, offers no cashback or card rewards, and lacks the comprehensive features needed for complete business operations such as built-in payables automation, expense management, or connections to Canadian banking rails.
Key features and limitations:
- Hold 40+ currencies with low FX fees
- Local USD, GBP, EUR account details
- No Interac e-Transfer support
- No cashback or card rewards
- Limited Canadian banking functionality
- No automated payables or expense tools
Verdict: Great for holding many currencies, but the missing Interac e-Transfer, cashback, and Canadian banking rails make it a partial solution for CAD-first businesses.
6. Scotiabank USD Business Account
Best for: Large businesses with complex banking relationships that require in-person advisory services.
Scotiabank's USD account follows the standard Big 5 bank model. It is held in Canada and depends on SWIFT wires for USD transfers, adding fees on every transaction. Monthly fees are high unless balance minimums are met, and the account lacks the automation and multi-currency tools that modern businesses need.
Key limitations:
- Canada-based USD account, no ACH
- High monthly fees unless balance minimums met
- $15-30 wire fees
- 2.5-3% FX markup
- No multi-currency card or cashback
- No accounting integrations
Verdict: Suited to large firms that value advisory relationships; the fees and SWIFT-only USD account are hard to justify for lean teams.
7. CIBC USD Business Operating Account
Best for: Businesses with heavy transaction volumes that prefer traditional banking infrastructure.
CIBC offers USD business accounts with unlimited transactions, but the Canada-based structure means all transfers use SWIFT rails. This results in wire fees on both inbound and outbound USD payments, plus FX markups of 2.5-3%. The account requires separate management from CAD operations, with no unified platform, multi-currency card, or integration capabilities with modern business tools. Monthly fees start at $65+ regardless of balance or usage.
Key limitations:
- No local USD account or ACH capability
- Wire fees on all USD transfers
- 2.5-3% FX markup
- High monthly fee ($65+)
- No multi-currency card
- No automation or integrations
Verdict: Unlimited transactions help high-volume businesses, but the $65+ monthly fee and Canada-based USD account still carry wire and FX costs.
The Real Cost of Traditional Bank USD Accounts
The term "USD account" at Canadian banks creates a misleading expectation. Businesses assume these accounts function like U.S. bank accounts, but they operate entirely from Canada. Every USD transfer, even to another USD account, routes through the SWIFT network, incurring wire fees and processing delays that local U.S. accounts avoid entirely.
Consider a business that receives a $10,000 USD payment and later pays a $5,000 USD vendor invoice. With a traditional Canada-based USD account, the inbound wire triggers a $17+ receiving fee, and the outbound vendor payment costs $30 in wire fees. If any portion needs conversion to CAD, a 2.5-3% FX markup applies on top. Across both transfers, the total cost reaches $172, nearly 2% of the transaction value.
Venn's approach eliminates these unnecessary costs. Inbound wires are free, and Sending $5,000 to the vendor via ACH costs $0-2 instead of $30. Conversions, when needed, use FX rates from 0.25% rather than 2.5-3%. Total savings exceed $150 on just these two transactions.
How to Choose the Best USD/CAD Business Account for Your Needs
Selecting the right multi-currency account depends on how your business actually uses USD and CAD. A business that regularly sends and receives U.S. payments has very different needs from one that occasionally holds foreign currency. Start by mapping your transaction patterns, then weigh each provider against the factors that matter most for your operations.
The most important distinction is whether the USD account is truly local or Canada-based, because this single factor determines whether you can use low-cost ACH transfers or are forced into expensive SWIFT wires.
Decision factors:
- Real local USD account vs. Canada-based
- FX rates 0.25-0.45% vs. 2.5-3%
- Transfer costs
- Multi-currency card
- Accounting integrations
- Unified platform
- Cashback and rewards
Calculate your total cost of banking by combining monthly fees, per-transaction charges, and FX markups across a typical month of activity. This full-picture view often reveals that low-fee or no-fee accounts with high FX markups cost far more than accounts with modest monthly fees and competitive conversion rates.
Why Venn Is the Best USD/CAD Business Account in Canada
Venn uniquely combines real local USD accounts with full ACH capability, true Canadian banking infrastructure, some of the lowest FX rates in Canada, and comprehensive business automation in one unified platform. No other provider matches this complete solution.
The infrastructure advantage sets Venn apart. Real local USD accounts send and receive ACH transfers, eliminating wire fees and enabling businesses to operate as U.S. locals. The Canadian account built on tier-1 banking infrastructure enables full functionality including Interac e-Transfer, bill payments, tax payments, and payroll. This dual capability means businesses operate seamlessly in both countries without the limitations that restrict other platforms.
Cost savings compound across every transaction. FX rates from 0.25% save thousands compared to traditional banks charging 2.5-3%. Free inbound wires and $0-2 ACH transfers slash transaction costs. The multi-currency card provides 1% cashback on card spend while automatically selecting the payment currency to avoid conversions. Additionally, Venn pays 2% interest on all CAD and USD balances, with a limited-time boost of up to 2.75% on CAD and up to 3.5% on USD balances (learn more), with no minimum balance requirements.
Venn eliminates the traditional tradeoffs between high-fee banks with poor technology and limited-feature fintechs with restricted functionality. The platform delivers a complete financial solution built specifically for Canadian businesses operating in multiple currencies.
How to Open a USD/CAD Business Account in Canada
Opening a multi-currency business account with Venn is a fully digital process. Rather than booking a branch appointment and waiting days for approval, businesses can apply online, often within minutes, and begin transacting in CAD and USD shortly after.
Before you start, gather the documents that verify your business and its owners. Having these ready keeps the application smooth and helps you get approved faster.
What you'll need:
- Business registration documents
- Proof of Canadian business address
- Director and beneficial owner identification
- Business number (BN) or incorporation documents
Get started with Venn and open your multi-currency account today.
FAQ
Q: What is the difference between a real local USD account and a Canada-based USD account?
A: A real local USD account, like the one provided by Venn, operates within the U.S. banking system, enabling direct, low-cost ACH transfers and faster payment processing. A traditional Canada-based USD account operates from Canada and may not support ACH transfers, often requiring slower and more expensive wire transfers for USD transactions.
Q: What is the true cost of operating a traditional USD business account?
A: The costs can be high. Big 5 banks may charge monthly account fees of $30–$65 or more, plus transaction fees for wires. The biggest cost can be the FX markup on currency conversions, where traditional banks may charge 2.5%–3.5%. In comparison, Venn offers FX rates as low as 0.25%, potentially saving businesses thousands annually when they make regular currency conversions.
Q: Can I send or receive ACH transfers from a Canadian business USD account?
A: Only if you have a real local USD account, such as the one provided by Venn. Traditional Canadian bank USD accounts generally cannot send or receive ACH transfers because they do not operate directly within the U.S. banking system, which can require businesses to use slower and more expensive wire transfers instead.
Q: Do I need separate accounts for CAD and USD, and can I integrate them with my accounting software?
A: With traditional banks, you may need separate accounts and logins for each currency. Modern platforms like Venn provide a unified multi-currency account for CAD, USD, GBP, and EUR, allowing you to manage multiple currencies from one dashboard. Venn also offers two-way sync with QuickBooks and Xero to help automate transaction categorization and reduce manual data entry.
Q: How long does it take to transfer USD internationally or to the U.S. from Venn?
A: Traditional bank wires can take 3–5 business days. With Venn's real local USD account, transfers may be significantly faster: ACH transfers can complete in 1–2 business days, while international wire recipients may typically receive funds the same or next business day, helping businesses pay suppliers and contractors more quickly.
*Based on internal analysis of total markups and FX fees charged by major Canadian financial institutions as of September 2026.
Disclaimer: This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Venn Software Inc or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional. We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.

Venn is all-in-one business banking built for Canada
From free local CAD/USD accounts and team cards to the cheapest FX and global payments—Venn gives Canadian businesses everything they need to move money smarter. Join 15,000+ businesses today.
Frequently asked questions
Everything you need to know about the product and billing.
Join 15,000+ businesses banking with Venn today
Streamline your business banking and save on your spend and transfers today
No personal credit check or guarantee.